Separate forecasts from orders
A signal expresses direction and conviction. Position sizing, rebalancing and execution determine how that forecast becomes a trading strategy.
Alpha & signals
AI agents develop trading hypotheses and strategy code. Stratmill also includes signal research components that evaluate forecasts, account for turnover and costs, and combine signals under a shared risk model.
Every evaluation is listed on the Alpha Signals page of your workspace. Combined signal books remain an engine capability.
signal_evaluation.pyresult = evaluate_signal(
forecast, next_return,
round_trip_cost=cost,
)
net_edge = result.net_edge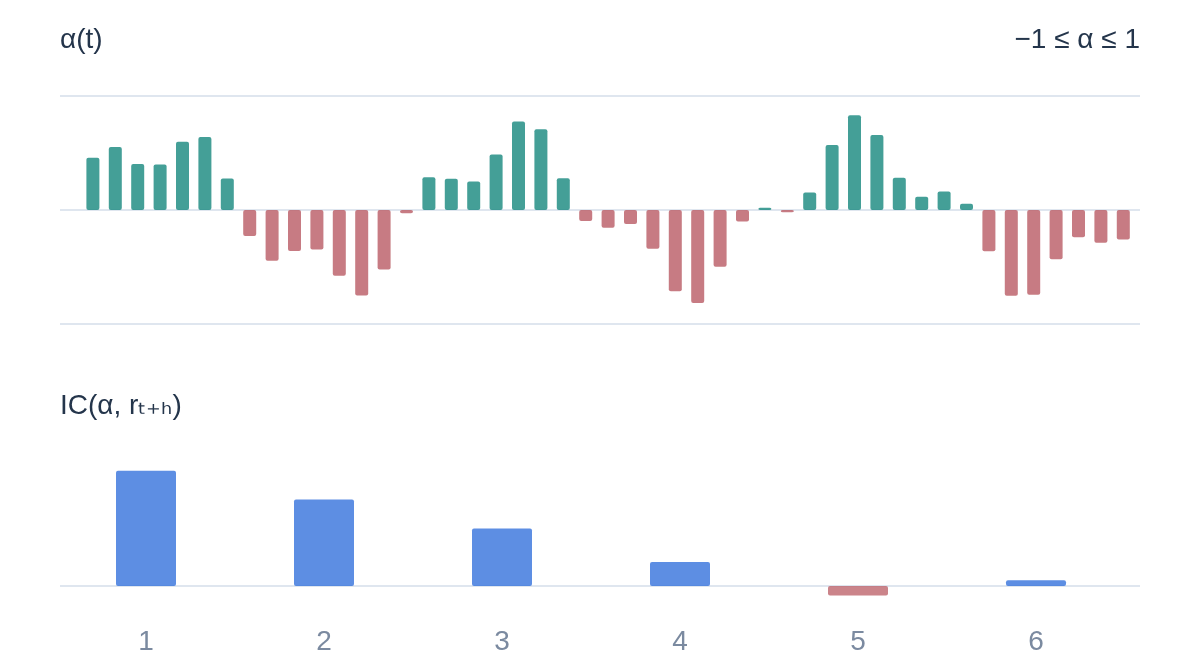
Illustrative example · not a live result
Interactive illustration
An AI-generated idea needs measurable evidence. Reveal successive observations to compare a forecast score with the return that followed it.
A positive correlation in this small example does not establish a tradeable edge. Check the forecast horizon, independent samples, turnover and costs before combining signals.
Next-bar return (%)
Forecast score
The first observations give only a fragile estimate.
New observations can weaken the apparent relationship.
Review the whole sample and its uncertainty before drawing a conclusion.
Explore how this stage contributes to the AI trading strategy factory.
A signal expresses direction and conviction. Position sizing, rebalancing and execution determine how that forecast becomes a trading strategy.
Signal evaluation considers information coefficient, statistical evidence, turnover, net edge and correlation with existing forecasts.
The signal library records every evaluation verdict, including the rejections, and the Alpha Signals page shows them. A forecast that disappears after costs is a useful research result.
A forecast can be useful on its own yet add little to a book that already carries the same exposure. Evaluate both its information and its contribution.
Define the proposed effect and forecast horizon.
Measure information, turnover and net edge.
Weight forecasts and size the combined exposure.
Inspect contributions and compare with the signal removed.
No single statistic turns a forecast into an approved strategy. Signal evaluation is upstream of strategy verification, backtesting and release review.
Scroll horizontally to see all columns.
| Measure | Question it answers | What to watch |
|---|---|---|
| Information coefficient | Does the forecast align with subsequent returns? | Sample size, uncertainty and the forecast horizon. |
| Turnover & net edge | Does the estimated effect survive the cost of following it? | Trading costs and forecast changes can consume the gross edge. |
| Correlation | Is this forecast similar to one already in the book? | A different name can still describe the same underlying bet. |
| Contribution | How is the combined book’s result allocated to its signals? | Recorded attribution is an allocation; compare a run without the signal to study its marginal effect. |
Alpha research searches for a predictive effect that may contribute returns beyond an existing exposure or benchmark. An alpha hypothesis is a claim to test, not a promise of excess returns.
On the Alpha Signals page of your workspace, the signal library. It lists every forecast evaluation the pipeline registered for your strategies, accepted or rejected, with its information coefficient, gross and net edge per period, cost, horizon and verdict. Filter by stage or verdict, search by strategy or instrument, and switch to platform strategies, whose evaluations every signed-in user can read.
Three. Baseline is the first full backtest, before any review or tuning. Optimized replay replays the optimised parameters on the data they were tuned on, so it is in-sample and never out-of-sample evidence. Final exam is the one read of the reserved final window, kept whether the strategy passed or not.
No. Live market indicators describe current market conditions. A research signal is a forecast evaluated against subsequent outcomes; an indicator alone is not evidence of a tradable edge.
The signal-book component combines weighted forecasts into a single position and manages its risk and rebalancing.
No. Signal acceptance is a research verdict. The resulting strategy still needs verification, testing, review and paper admission; live execution additionally requires account-specific authorization and operational checks.
No. The book records a share-based allocation of P&L. A comparison with and without a signal provides another view of its contribution, but neither removes uncertainty about future behavior.
See how AI agents, testing engines and execution controls work together across the strategy factory.
Stratmill is an AI trading strategy platform, not financial advice or a broker. Backtest and paper results are hypothetical. Trading involves risk of loss.